Admitted vs surplus lines: 6 differences on your policy
Admitted insurers are licensed by California, but surplus lines insurers aren't. See the 6 differences that show up on your policy, with a table.
Comparisons and rankings for California homes
For a house you own and live in, the HO-5 covers the most on its standard wording. The HO-3, HO-2, HO-1 and HO-8 follow in that order. The HO-4 and HO-6 aren't ranked, because they're written for renters and condo owners.
Admitted insurers are licensed by California, but surplus lines insurers aren't. See the 6 differences that show up on your policy, with a table.
Make 2 quotes match on the house, the form, the limits and the deductible before you compare price. Here are 10 steps and a worksheet for California.
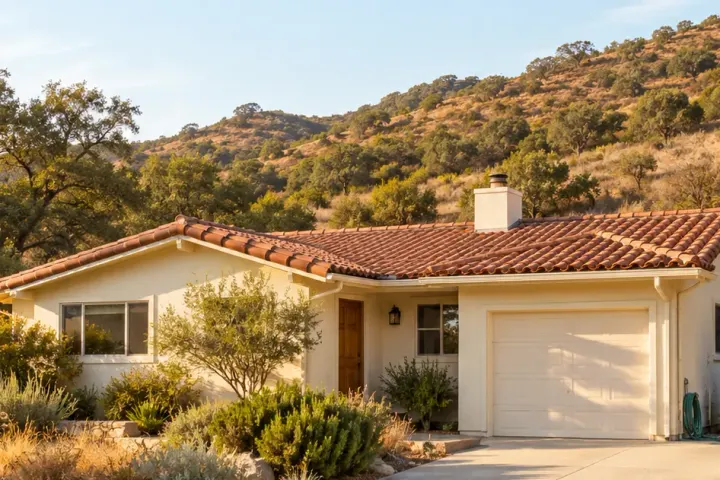
Slate and clay tile last the longest but weigh the most. See 8 roof materials ranked by lifespan, with weight, fire rating and cost for a California home.
Pick any 2 forms. Where they match, the row folds into one line, so the differences are what's left to read.
| HO-3Special Form | HO-5Comprehensive Form | |
|---|---|---|
| Place on our ranking | 2nd | 1st |
| The house | Open perils on both | |
| Your belongings | 16 named perils | Open perils |
| Written for | A home you own and live in on both | |
| Liability and medical payments | Included on both | |
| Earthquake and flood | Not covered on both | |
Based on the 2011 ISO model forms filed with the California Department of Insurance. Your own policy's wording decides what it covers.
Homeowners policy forms and the parts of a policy compared, read from the filed wording, plus the products people confuse with insurance.
How a surplus lines home policy reads on paper next to an admitted one: the notice, the fees, the tax and the cancellation terms.
Roof materials, shingles and underlayment compared for California homes, with lifespan, weight and fire rating from published sources.
Pipes, water heaters, heating, insulation, foundations and floors compared side by side for a California house.
We read the source before we compare anything. For a policy form, that's the model wording filed with the California Department of Insurance. Every story lists its sources at the end.
We rank options, never companies. You won't find a named insurer, agency or quote service ranked here, and we don't quote prices.
When a fact changes, we fix the story and change its Updated date.